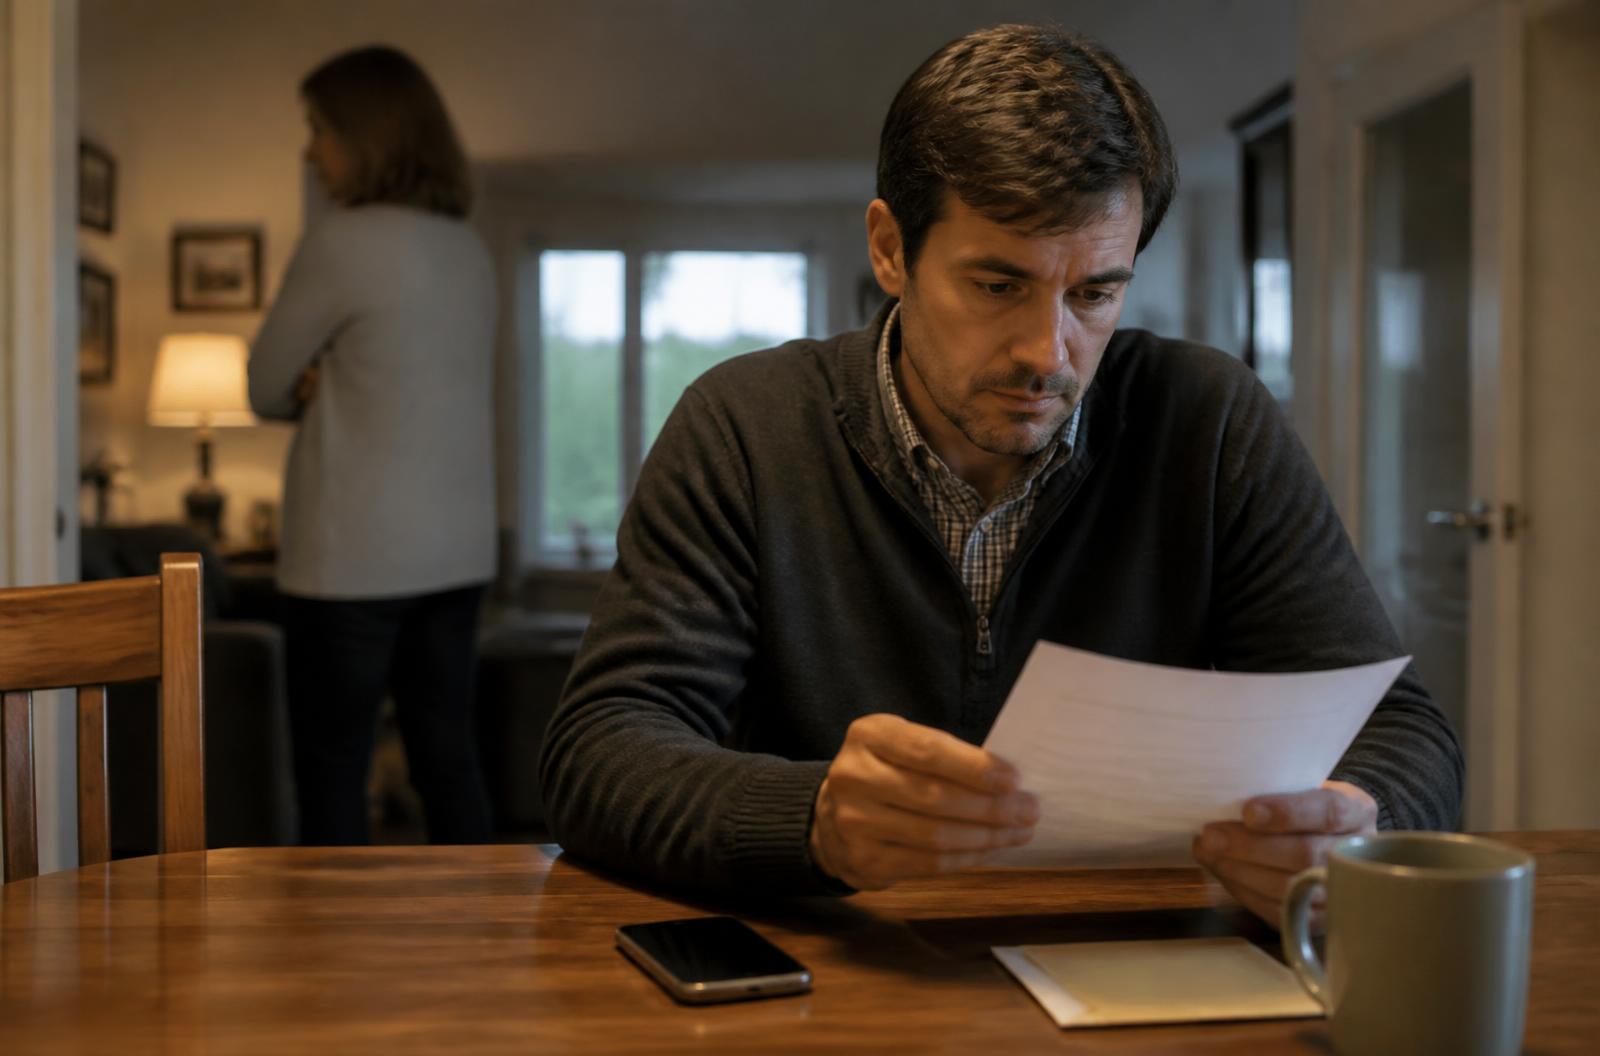
The charge was small enough that he almost ignored it.
A hotel. One night. Midweek.
He stared at the line item longer than he wanted to admit.
His wife had not mentioned a trip.
He checked the date again.
Then he checked the statement before it.
There were other charges he did not recognize.
Not hotels. Groceries. Gas. A pharmacy. A few online purchases.
Normal things, except they were on a card he did not know existed.
By the time she got home, he had already imagined the worst.
He asked about the hotel first.
She looked confused.
Then embarrassed.
There was a card he did not know existed.
The hotel charge was not what he thought.
It was part of a family emergency she had put on a credit card months earlier and never told him about.
But once they started talking, the hotel charge became the least important thing on the statement.
The hotel charge was not the real secret.
There were balances on several cards.
There were transfers from one account to another.
There were months where one card had been used simply because there was no room left in the budget after the other payments went out.
She had been trying to keep the household running without admitting how bad the debt had become.
What started as a few private purchases had turned into a pile of balances she could no longer manage quietly.
That night, they added everything together.
The total was far worse than he expected.
But the part that shocked them most was not just the balance.
It was how much they had been paying every month while still feeling like they were standing still.
When a personal secret becomes a financial pattern
This is where a personal secret becomes a financial pattern.
People with large credit card balances are often not ignoring the debt. They are making payments.
The problem is that high interest can consume a large share of those payments before the principal moves very much.
That creates a dangerous illusion: money is constantly leaving the bank account, but the overall debt barely seems to change.
Starting balance
$20,000
24% APR, assumed
$600 assumed monthly payment
$600 paid. About $200 of balance reduced.
What this means
A payment can keep an account current while reducing the balance far less than expected.
If this payment pattern feels familiar, you can see what options may be available before deciding what to do next.
The Real Problem Wasn't the Hotel Charge. It Was the Debt She Had Been Trying to Outrun.
Once debt becomes large enough, the monthly payments can start dictating the rest of the household budget.
People delay purchases, move balances, use one card while paying another, or quietly absorb expenses they are too embarrassed to discuss.
The secrecy is often a symptom of the pressure, not the cause.
Eventually, the math forces a different question.
“How do we keep making all of these payments?”
becomes
“What other options do we actually have?”
Check Your Options
If you are carrying substantial unsecured debt and monthly payments are no longer creating meaningful progress, it may be worth understanding what alternatives may be available.
Check Your OptionsThis may be worth exploring if:
- You have $20,000+ in unsecured debt.
- You are making payments but the balances remain stubbornly high.
- You are using credit to cover normal household expenses.
- You have moved balances or used one card to create room on another.
- The debt has become stressful enough that you avoid talking about it.
See What Debt Relief Options May Be Available
A quick review can help you understand what paths may be worth considering based on your situation.
See My Options