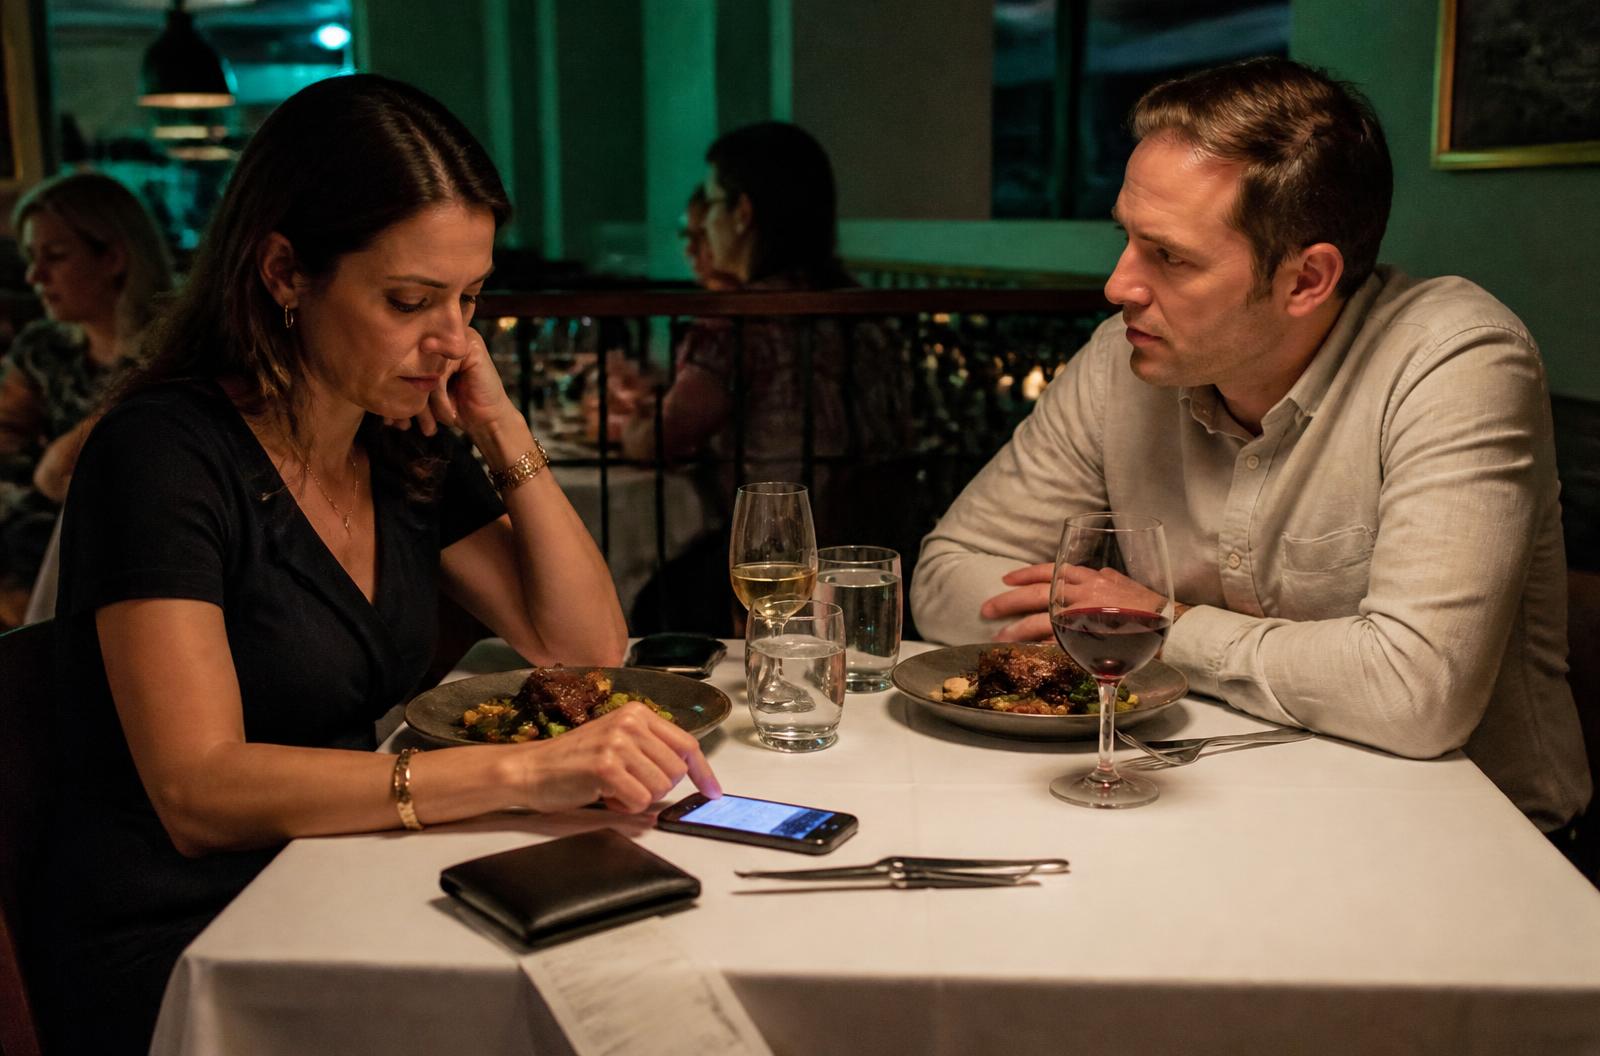
Their anniversary dinner was supposed to be easy.
A quiet table. A bottle of wine. One night where they did not talk about work, errands, or bills.
For most of the evening, it worked.
Then her phone lit up.
She looked at the screen and flipped it face down almost immediately.
Her husband noticed.
“Everything okay?” he asked.
“Yeah. Just spam.”
A few minutes later, the phone buzzed again.
This time he caught a few words on the screen before she moved it.
Payment due.
He asked which card it was.
She hesitated.
“Which card?”
a short pause before the reveal.
That pause changed the whole dinner.
There was a credit card he did not know about.
She had opened it three years earlier during a stretch when money was tight. At first, the balance was small enough that she was sure she could handle it herself.
So she never mentioned it.
Then came groceries. A repair. A family expense. A few months where the card became the easiest way to keep everything moving.
The balance grew.
She kept paying it. She also kept hiding it.
Every time she thought she was about to get ahead, interest and new expenses seemed to erase the progress.
By the time that anniversary dinner arrived, the secret was no longer one card with a manageable balance.
It had become part of a much larger debt problem.
The dinner ended early.
At home, they opened the accounts together and finally looked at everything in one place.
What shocked them was not only how much they owed.
It was how much they had been paying without feeling like the balances were meaningfully changing.
When the secret becomes a math problem
This is where the story stops being only about secrecy and becomes a math problem.
Many people with large credit card balances are making payments every month. The problem is that a payment is not the same thing as meaningful progress.
When interest rates are high, a large share of each payment may go toward interest before it reduces the balance.
That can make a debt problem feel strangely invisible: money keeps leaving the checking account, but the total barely seems to move.
Starting balance
$20,000
24% APR, assumed
$600 assumed payment
$600 paid. About $200 of balance reduced.
What this means
A payment can keep an account current while reducing the balance far less than expected.
If this payment pattern feels familiar, you can see what options may be available before deciding what to do next.
Why One Hidden Card Can Turn Into a Much Bigger Problem
A credit card can begin as a temporary fix and slowly become part of the household budget.
Once balances grow, the required payments compete with groceries, rent or mortgage, utilities, transportation, and everything else that still has to be paid.
People often respond by moving balances, using another card for breathing room, or making the payment that feels most urgent that month.
The result can be years of activity without the kind of progress they expected.
Eventually the question changes.
“How do I keep up with all of these payments?”
“What other options do I have?”
Check Your Options
If you are carrying substantial unsecured debt and monthly payments are no longer creating meaningful progress, it may be worth understanding what alternatives may be available.
Check Your OptionsThis may be worth exploring if:
- You have $20,000+ in unsecured debt.
- You are making payments but still feel stuck.
- You are using credit to cover expenses because monthly debt payments are absorbing too much cash flow.
- You have moved balances or opened new cards just to create breathing room.
- You want to understand your options before the debt puts even more pressure on your household.
See What Debt Relief Options May Be Available
A quick review can help you understand what paths may be worth considering based on your situation.
See My Options