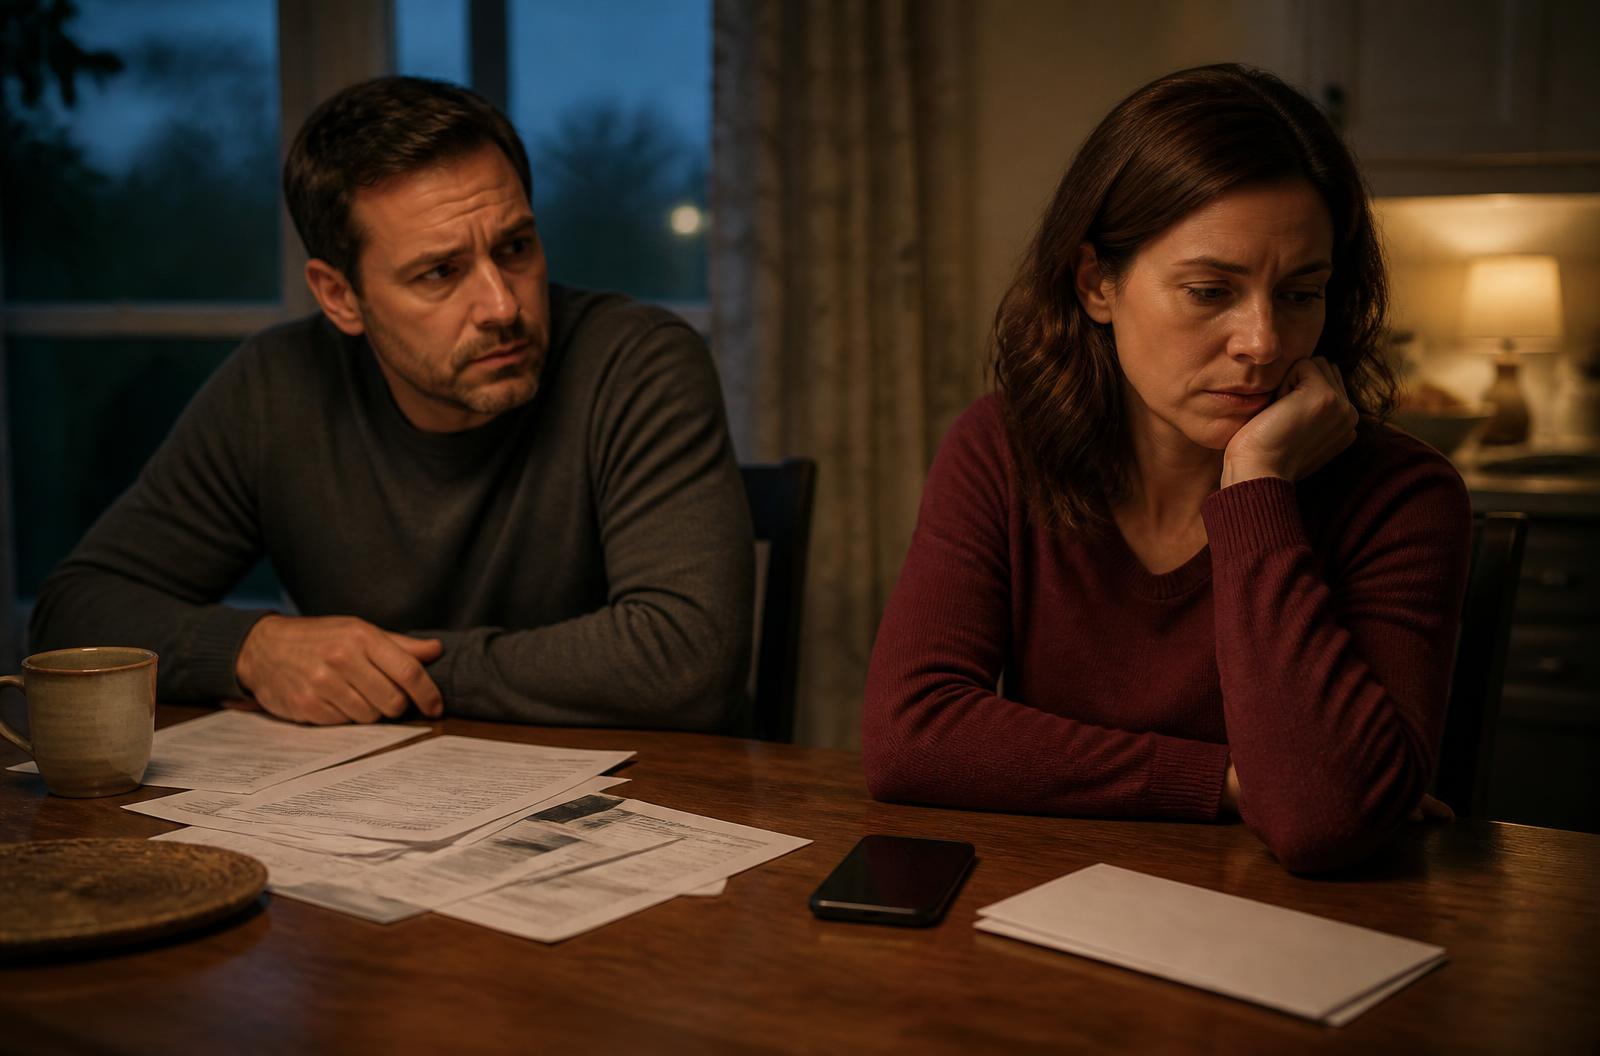
At first, he thought he was imagining it.
His wife had become strangely protective of her phone. She would close banking apps when he walked into the room. Credit-card envelopes disappeared from the counter almost as soon as they arrived.
When he asked if everything was okay, the answer was always the same: ‘Yeah. Just tired.’
Then he noticed she had stopped talking about money altogether.
No casual comments about the grocery bill. No complaints about the electric bill. No mention of the cards they used for everyday expenses.
He started filling in the blanks himself.
Maybe there was someone else.
One night, after another short conversation ended with both of them frustrated, he finally asked the question he had been avoiding.
“Are you hiding something from me?”
She was.
But it was not an affair.
It was debt.
More than $42,000 spread across several credit cards.
Some of it started with normal expenses. Groceries. A car repair. A family trip they said they would pay off later.
Then balances rolled over. Interest piled up. One card was used to create breathing room while another was being paid.
Month after month, she kept making payments and kept telling herself she would get the balances under control before he ever needed to know.
Instead, the numbers got bigger.
What scared her most was not just the amount. It was how little progress the payments seemed to create.
That night, they put every balance on the table.
For the first time, the problem was not hidden anymore.
It was not an affair. It was $42,000 in debt.
Once the full picture was visible, the question changed from what had been hidden to what they could do next.
See What Options May Be AvailableWhat the statements revealed
This is the part many people with large credit card balances do not fully see until they put every statement side by side.
Making payments can keep the accounts current without meaningfully reducing the total debt.
When interest rates are high, a large portion of a monthly payment may go toward interest before it touches the principal.
That is how someone can pay hundreds, or even more than a thousand dollars, every month and still feel like the balances barely move.
Starting balance
$20,000
24% APR, assumed
$600 assumed payment
$600 paid. About $200 of balance reduced.
What this means
A payment can keep an account current while reducing the balance far less than expected.
If the same pattern feels familiar, you can see what options may be available before deciding what to do next.
The Secret Was Not Just the Debt. It Was How Hard It Had Become to Escape It.
Once balances become large, the emotional problem and the math problem start feeding each other.
People avoid opening statements because the numbers are stressful. They make the minimum or routine payment because it feels safer than confronting the full picture.
Meanwhile, interest can keep consuming a meaningful share of what they send each month.
Eventually the question changes.
“How do I keep this hidden and keep making the payments?”
“What options do we actually have?”
Check Your Options
If you are carrying substantial unsecured debt and monthly payments are no longer creating meaningful progress, it may be worth understanding what alternatives are available.
Check Your OptionsThis may be worth exploring if:
- You have $20,000+ in unsecured debt.
- You are making payments but your balances remain stubbornly high.
- Debt payments are creating stress inside your household or relationship.
- You are using one card to create breathing room while paying another.
- You want to understand your options before the situation gets worse.
See What Debt Relief Options May Be Available
A quick review can help you understand what paths may be worth considering based on your situation.
See My Options